Market Snapshot: September 2026
Summary
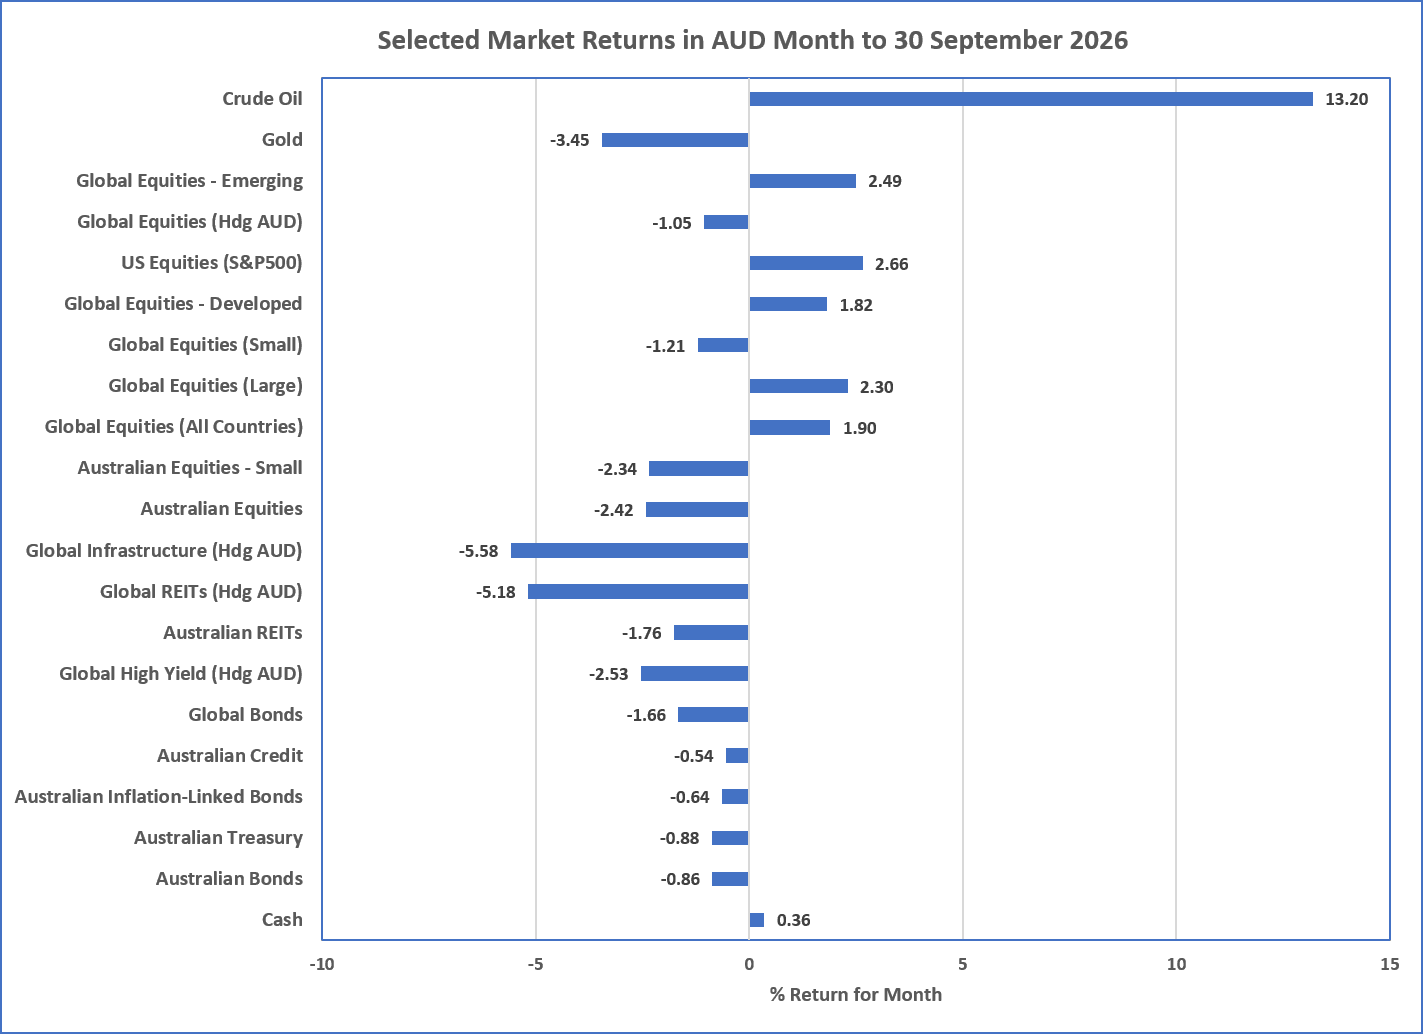
- The continuing Iran War has maintained high energy prices, feeding high inflation, and in September all major western economies increased their cash rates by 25bps, and this included Australia. The big financial news was the much higher bond yields, which means the high levels of government debt is being funded at their highest levels for around 15 years. These high bond yields fed into weaker sharemarkets as valuation hurdles became just a little bit higher.
- The best performing asset class (aside from energy) in September was Emerging Markets which was up a reasonable 2.5%. Whilst US sharemarkets declined a little during September, when converted back to Australian dollars, it also ended up over 2% as the Australian dollar declined by over 3%.
- Economically, inflation persists at higher than desired levels, unemployment remains relatively low but the persistent inflation and higher cash rates suggest economic weakness is very possible over the next 12 months.
- Our core investment message remains due to persistent downside risks from high sharemarket valuations in USA and the energy crisis. This means disciplined risk management rather than aggressive position changes. Shares continue to offer an attractive risk premium in specific markets, as do conservative bonds, but returns may be challenged from occasional short-term volatility. Avoiding panic (selling) decisions continues to be a crucial investment issue today for long-term investors.
Chart 1: Higher bond yields … weak sharemarkets and even weaker real asset returns
Source: Morningstar
What happened last month?
Markets & Economy … bond yields continue to rise
-
September was a similar month to August insofar that bond yields are the primary news and much much higher; but this time across all terms
and not just 30 years … yields have increased from cash to 10 years to 30 years, as the higher energy prices continued the higher for
longer inflation theme.
- Central banks increased rates by 25bps across USA, Australia, Europe, and Japan during September. In the USA this was seen as a positive, particularly as the new governor showed he is not doing what Trump wants (and Trump wants a rate decrease) and is focusing on keeping inflation manageable.
- The higher yields resulted in weak sharemarkets with many negative returns as the higher yields increased the valuation hurdle for all assets. The Australian market performed poorly (down 2.4%) and this was also driven by very weak consumer sentiment, concerns about the economy, thereby resulting in significant weakness in sectors such as consumer discretionary (e.g. Wesfarmers). Whilst Australia’s tech sector also declined significantly, a few AI-aligned stocks helped the US market almost breakeven but fortunately the weak Australian dollar (down over 3%) meant investors had positive global returns.
- Economic growth around the world is slightly positive but not helped by the inflationary situation and continued tariff war. However, unemployment continues at low levels which augurs well for the economy but also keeps upward pressure on inflation and future central bank interest rate decisions.
Outlook …
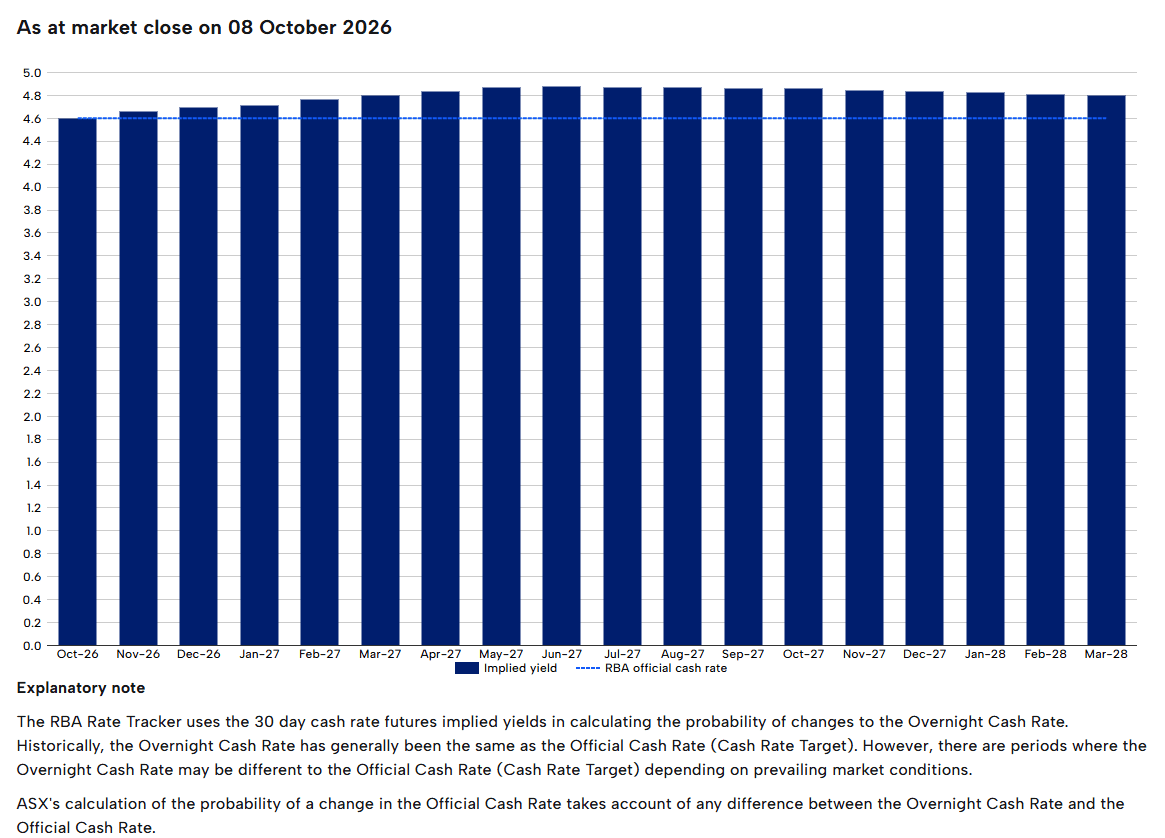
- The continuation of higher inflation in Australia keeps a strong likelihood of more rate increases as markets price up to 2 more … this is a significant change from recent months as markets envisage higher inflation for longer than previously anticipated.
- Bond yields around the world have also continued to increase and expected returns for fixed interest are also consolidating at over 5%pa over the next 5-10 years. These expected returns are at their highest levels for many years.
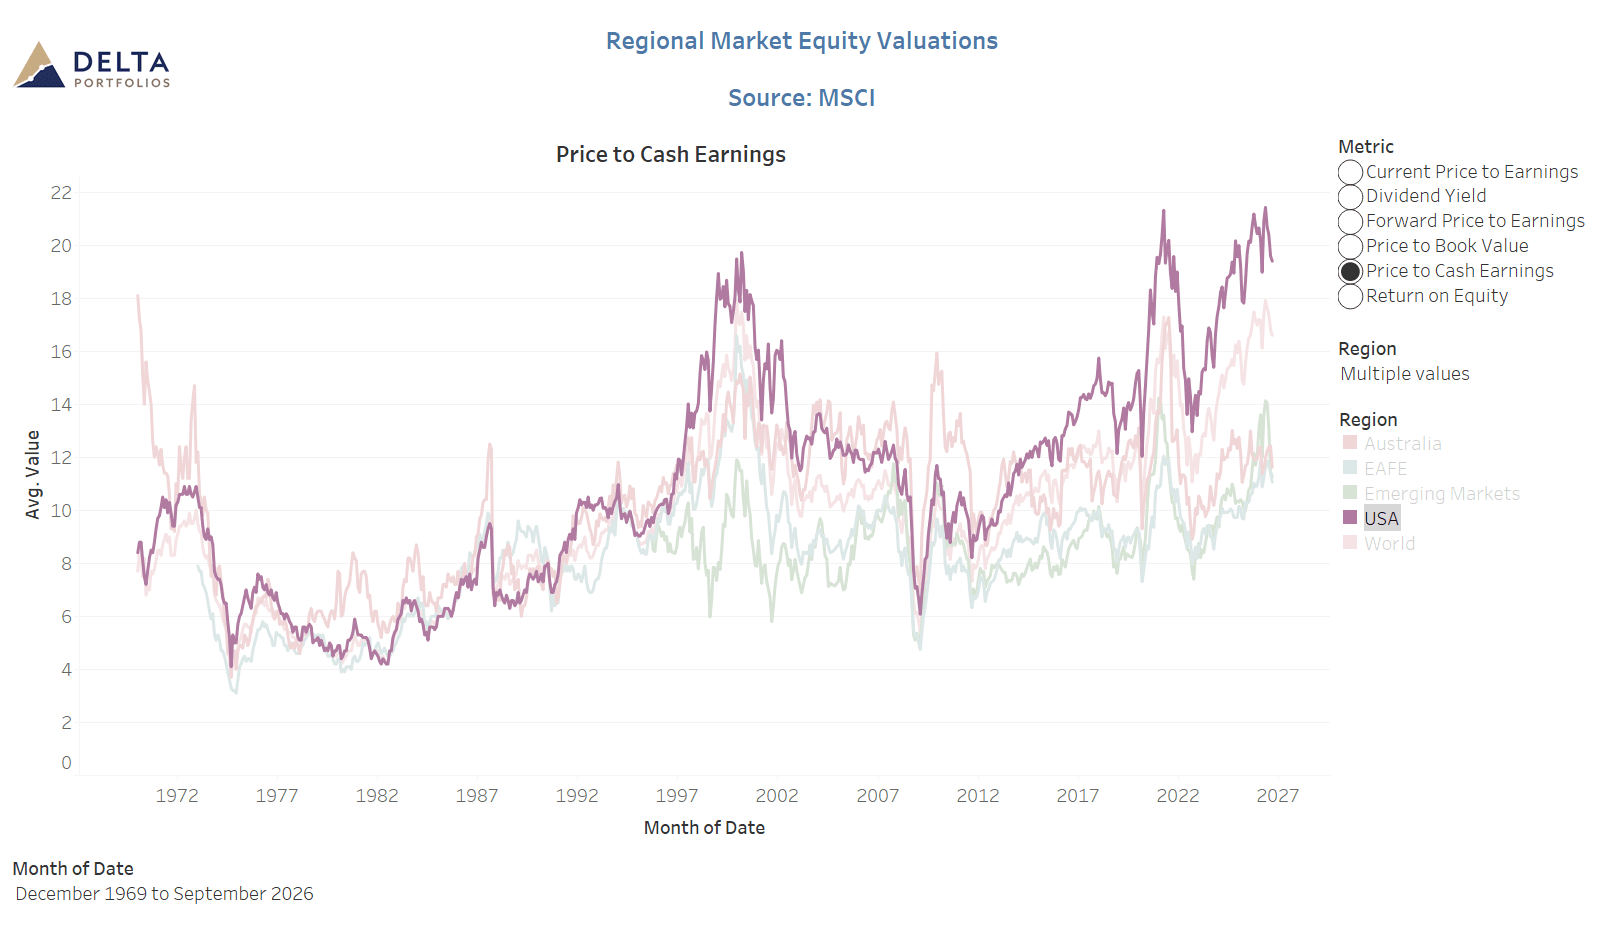
- At the risk of crying wolf, US markets continue near record high valuations and are forecast to be weaker than non-USA sharemarkets over the next 10 years. As previously mentioned, this doesn’t mean any imminent crash is likely, and returns may continue to be good over the short-term, particularly whilst the AI capex has a long time to go yet, but caution should always be appropriate with expensive markets.
- Our core message remains as we continue to believe portfolios should be underweight USA shares and high yield (junk) bonds due to these near record high valuations. By comparison, defensive Cash and bond portfolios both global and in Australia, are providing strong relative expected returns at over 5%pa.
- Our current beliefs are that new investors should dollar cost average into sharemarkets and long-term investors should stay invested for the long-term but should expect and get used to higher volatility.
- Diversification continues to be essential. Maintaining a balance between domestic and global exposures remains a prudent approach as 2026 unfolds. Rebalancing as pricing opportunities arise also continues to be appropriate for established portfolios.
Major Market Indicators
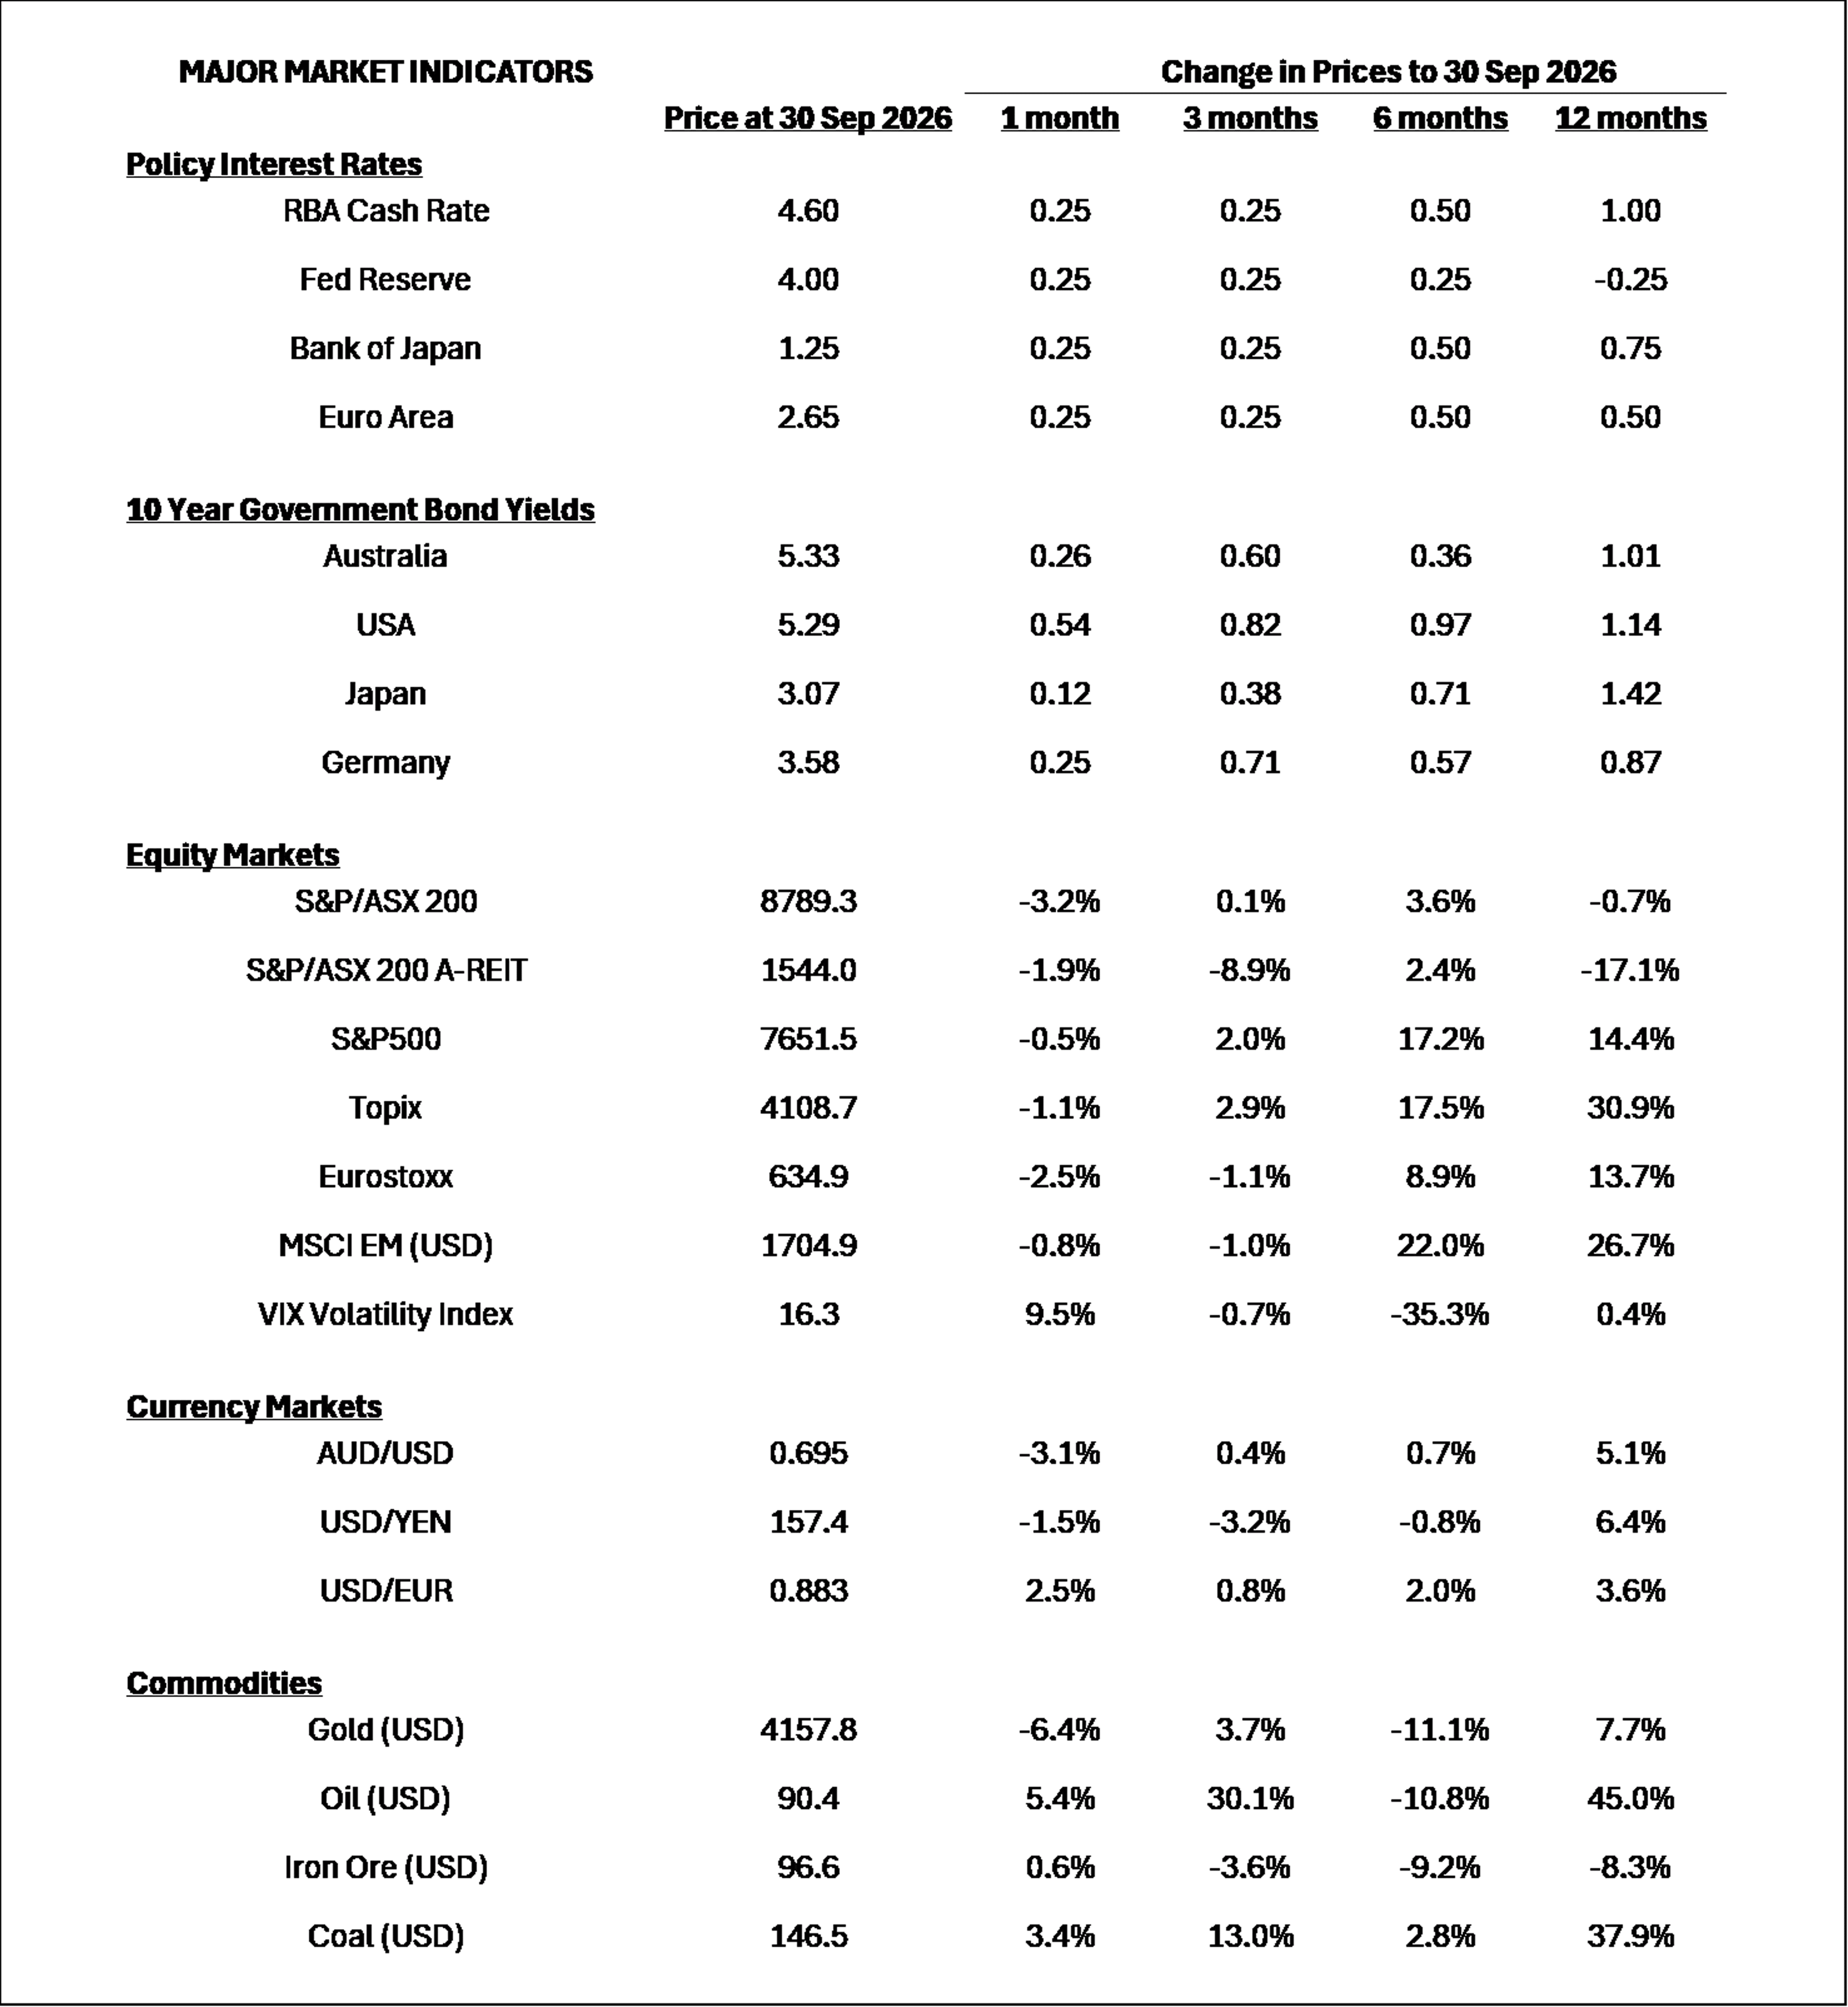
Sources: Morningstar, Trading Economics, Reserve Bank of Australia
30 September Market Valuations since 1969 – Price to Cash Earnings … improvement in USA but still high
Rising cash rate expectations by the Australian market … pricing in 1 more rise
McConachie Stedman Financial Planning Pty Ltd is a Corporate Authorised Representative of MCS Financial Planning Pty Ltd | ABN 11 677 710
600 | AFSL 560040
General Advice Warning
The information provided in this article is for general information purposes only and is not intended to and does not constitute formal
taxation, financial or accounting advice. McConachie Stedman does not give any guarantee, warranty or make any representation that the
information is fit for a particular purpose. As such, you should not make any investment or other financial decision in reliance upon the
information set out in this correspondence and should seek professional advice on the financial, legal and taxation implications before
making any such decisions.